
Home Insurance in Wichita Falls, Texas: Tornado and Hail Considerations
If you own a home in Wichita Falls, you live in one of the most weather-tested parts of Texas. Tornadoes, severe thunderstorms, and big hail are not rare headlines here – they are part of the risk picture insurers study every time they price a policy. From my seat as a Texas agent, I see homeowners in Wichita County get wildly different quotes for what seem like similar homes.
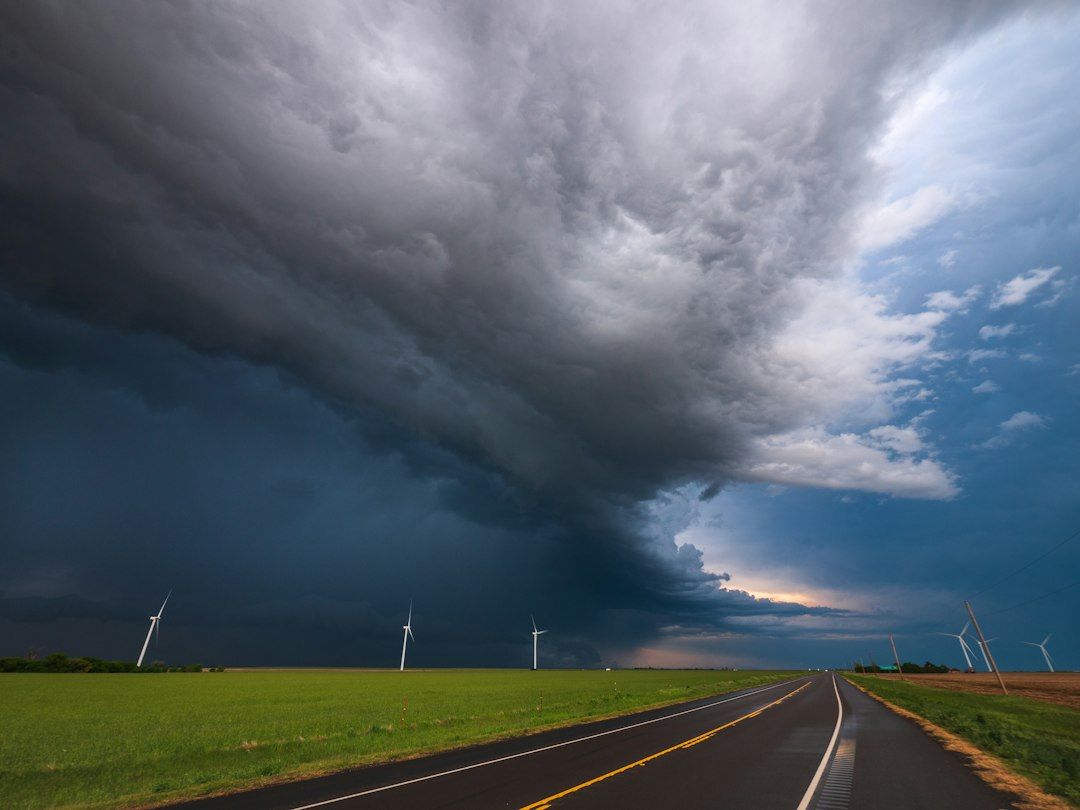
Understanding Home Insurance in Wichita Falls, TX: Tornado & Hail Realities
If you own a home in Wichita Falls, you live in one of the most weather-tested parts of Texas. Tornadoes, severe thunderstorms, and big hail are not rare headlines here - they are part of the risk picture insurers study every time they price a policy.
From my seat as a Texas agent, I see homeowners in Wichita County get wildly different quotes for what seem like similar homes. The biggest reason: how each carrier views tornado and hail exposure, and how they structure your deductibles around that risk.
Handled correctly, you can still get solid protection without overpaying. Handled poorly, one bad storm could wipe out your savings.
Why Tornado Alley Risk Hits Wichita Falls Home Insurance Quotes Hard
When we talk about home insurance Wichita Falls TX pricing, we are really talking about one thing: wind and hail. Fire, theft, and liability matter, but they are not what drives the big swings in your quote.
1. Tornado history and carrier memory
Wichita Falls sits in what meteorologists often refer to as part of "Tornado Alley." The city’s history is etched with major events like the 1979 "Terrible Tuesday" tornado, which the National Weather Service still lists as one of the costliest and deadliest tornadoes in U.S. history at the time.
Insurers use decades of storm data from sources such as NOAA’s Storm Prediction Center and the National Weather Service. That data shows:
- North Texas, including Wichita County, regularly experiences strong severe-thunderstorm outbreaks.
- Many of these include damaging straight-line winds and tornadoes strong enough to rip roofs, siding, and windows apart. Carriers do not forget those patterns. They build them directly into your base premium and especially into your wind and hail deductibles.
2. Hail frequency and roof claims
According to NOAA’s Storm Events Database and national insurance studies, Texas consistently ranks among the top states in both the number of hail events and total hail losses each year. Wichita County is solidly in that corridor.
That matters because:
-
Roof claims are among the most common and expensive home claims in North Texas.
-
A single storm can prompt hundreds or thousands of roof replacements in a small area. So for insurance Wichita Falls TX carriers:
-
Roof age, material, and shape often matter more than interior finishes.
-
A new Class 4 impact-resistant roof might save you more on premium than a full kitchen remodel ever will.
3. Smaller market, fewer carrier options
Compared with Dallas-Fort Worth, Wichita Falls is a smaller metro. Some national carriers limit their appetite in higher-risk areas or only write certain roof ages and deductible options. That can:
- Shrink the number of companies willing to quote your home.
- Push more of the wind and hail cost onto you through higher deductibles or more exclusions. If you want a deeper statewide picture of how carriers think, it can help to read a broader resource like our Texas Homeowners Insurance Quotes Guide and even compare with other secondary markets such as Abilene, TX homeowners insurance. The same forces that affect those communities are at work in Wichita Falls too.
How Carriers Structure Home Insurance Wichita Falls TX Policies
Even when two quotes show the same "coverage limit," the details under the hood can be very different. Here is how most companies adjust home insurance Wichita Falls TX policies in response to tornado and hail exposure.
Split deductibles: all-perils vs wind and hail
In lower-risk areas, many homeowners have one "all-perils" deductible that applies to almost any type of claim (other than special items like hurricane or named storm on the coast). In Wichita Falls, it is common to see:
-
One deductible for most claims (fire, theft, water damage, etc.).
-
A separate, higher deductible for wind and hail. Typical patterns I see:
-
All-perils deductible: a flat amount, like $1,000 or $2,500.
-
Wind/hail deductible: a percentage of your Coverage A (dwelling) limit. Example:
-
Your home is insured for $300,000.
-
All-perils deductible: $2,000.
-
Wind/hail deductible: 2%. A tornado damages your roof and siding. Because the loss is wind-related, your deductible is 2% of $300,000, or $6,000. Many homeowners are surprised by this gap because they only remember the smaller dollar figure.
The Texas Department of Insurance has written about the growth of percentage-based deductibles in higher-risk parts of the state, especially for wind and hail. In Wichita Falls, that is standard practice, not an exception.
Roof coverage: replacement cost vs actual cash value
To control hail exposure, some carriers now offer or push:
- Replacement cost on the home overall, but
- Actual cash value (ACV) on the roof after it reaches a certain age. With ACV, the insurer subtracts depreciation for age and wear before paying. On an older roof, that can easily turn a full replacement into a much smaller check.
Other companies may:
- Charge more to keep full replacement cost on older roofs, or
- Require you to upgrade to an impact-resistant product to qualify. This is one reason I always tell Wichita Falls homeowners: when you compare quotes, do not just look at the premium. Look very closely at how your roof is insured and what your wind/hail deductible is. Our article on how accurate instant home insurance quotes are for Texas homes explains why the quick online number rarely tells this whole story.
Cosmetic damage limitations
Given the frequency of hail in North Texas, some carriers add "cosmetic damage" exclusions on metal roofs, gutters, or siding. These endorsements say that if a storm only dents a metal surface without puncturing or compromising function, it may not be covered.
That is another way companies manage the high claim volume associated with frequent, less-catastrophic hailstorms. As a homeowner, you need to know if that language is in your policy before the sky turns green.
Discounts and credits that actually help here
Because wind and hail are such a big driver of loss, carriers often reward:
- Class 3 or 4 impact-resistant roofing materials.
- Professionally installed storm shutters or rated impact windows.
- Upgraded garage doors and roof tie-downs that better resist high winds. These credits often stack with more general savings, like home and auto bundling in Texas. In a high-risk market like Wichita Falls, smart mitigation can offset a lot of the "tornado alley" surcharge.
For a broader discussion of wind and hail strategies statewide, see our guide on Texas hail and wind protection without breaking the bank.
Smart Deductible Strategies For High Wind And Hail Risk Homes
Now, the practical part: how should you actually structure your deductibles in Wichita Falls? This is where I spend a lot of time with clients, because there is no one-size-fits-all answer.
1. Start with your emergency fund
Before we talk about "1% vs 2% vs 3%," I always ask:
- How much cash could you realistically come up with inside 30 to 60 days if a storm severely damaged your roof and exterior? That number is your real maximum deductible. If your emergency savings are thin, a 3% wind/hail deductible can be a serious problem.
For example, with a $350,000 home:
- 1% wind/hail deductible = $3,500 out of pocket.
- 2% = $7,000.
- 3% = $10,500. On paper, raising deductibles lowers premium. In practice, I have seen families delay needed repairs after a storm because they simply could not afford their share. That is not a situation you want to be in after a major tornado outbreak.
2. Consider a split strategy: higher wind/hail, moderate all-perils
One useful structure for home insurance Wichita Falls TX policies is:
-
Keep a moderate, manageable all-perils deductible (for kitchen fires, water leaks, theft).
-
Accept a somewhat higher wind/hail percentage if needed to keep the premium reasonable. Why this works:
-
You are more likely to have a non-wind claim that you want to turn in at lower amounts (like a sudden plumbing leak).
-
Wind and hail losses are often big enough that even with a higher deductible, it is still worth filing the claim. The key is to run the numbers both ways. Sometimes increasing your wind/hail deductible from 1% to 2% saves a meaningful amount. Other times in Wichita Falls, the savings are surprisingly small. An experienced agent can show you side-by-side quotes so you are not guessing.
3. Match deductible choices to your roof and home age
Your roof type and age should also influence your deductible strategy:
- New impact-resistant roof: You might safely carry a slightly higher wind/hail deductible because your risk of major damage is somewhat reduced and you are gaining premium credits.
- Older, worn roof: A high wind/hail deductible plus ACV roof coverage is a double hit. In that case, I usually recommend either:
- Negotiating better roof terms, or
- Keeping the wind/hail deductible as low as you can afford until you replace the roof. Insurers are increasingly data-driven about roof condition (some even use aerial imaging). Aligning your deductible with the real risk of your particular home is smarter than picking the lowest price on a screen.
4. Remember: tornado risk is not your only exposure
While tornadoes and hail are the headliners, Wichita Falls homeowners also have to think about:
- Straight-line wind from severe thunderstorms.
- Occasional flooding near creeks or rivers after heavy rain. Standard homeowners insurance excludes flood, which must be purchased separately through the National Flood Insurance Program (NFIP) or private markets. If you are near the Wichita River or another low-lying area, it is worth reading our Texas Flood Insurance Essentials guide and getting a separate quote.
Properly layering homeowners, wind/hail deductibles, and optional flood coverage is the best way to build a "whole weather picture" for your property.
5. Use a local-focused advisor, not just an app
Many Wichita Falls homeowners start with an instant online quote. That is fine for a ballpark, but those tools often:
- Default to higher wind/hail deductibles.
- Hide key details like ACV roof coverage or cosmetic damage exclusions in the fine print. We break down these limitations more in our article on how accurate instant Texas home quotes really are.
For a high-risk area like Wichita Falls, it usually pays to sit down with a Texas-based independent agency that knows which carriers are competitively and fairly pricing your local tornado and hail risk.
Bringing It All Together For Wichita Falls Homeowners
Living in Wichita Falls means accepting real weather risk. That is part of life in North Texas. It does not mean you are at the mercy of the insurance market.
If you understand how tornado and hail exposure shapes insurance Wichita Falls TX pricing, you can:
- Recognize when a quote looks cheap because the wind/hail deductible is sky-high or the roof is ACV.
- Decide how much risk you can safely keep through your deductible vs how much you transfer to the carrier.
- Invest in improvements like impact-resistant roofing that lower both your actual risk and your premium. Good coverage here is not about finding the absolute lowest price. It is about building a structure that can realistically carry you through the next big storm without derailing your finances. That means matching deductibles to your savings, your roof condition, and your long-term plans for the home.
BIG - Brock Insurance Group
At BIG - Brock Insurance Group, we work with homeowners across Texas, including high-risk weather markets like Wichita Falls, to untangle these decisions. As an independent agency, we can compare multiple carriers that write home insurance Wichita Falls TX risks and show you exactly how each one handles:
- Wind and hail deductibles.
- Roof coverage and exclusions.
- Discounts for impact-resistant materials and home updates. Instead of a one-size online quote, we walk through realistic storm scenarios and pick deductibles you can actually afford if a tornado or hailstorm hits. We can also coordinate your home coverage with your auto and other policies to find smart, not flimsy, savings.
Reach out to learn how we can help meet your needs. Let’s work together to build a Wichita Falls home insurance plan that respects both your budget and the storms we all know are coming.
Need coverage advice? Let’s talk.
Get a fast, no-pressure quote and guidance tailored to your needs.