
El Paso, TX Insurance Companies: Border-City Home and Auto Considerations
If you live in El Paso, you already know we are not “just another Texas city.” We are a true border community with daily international traffic, desert weather that can turn dangerous quickly, and neighborhood-level crime trends that do not always match the rest of the state. Those realities can shape everything from your deductibles to how (and where) your auto liability applies.
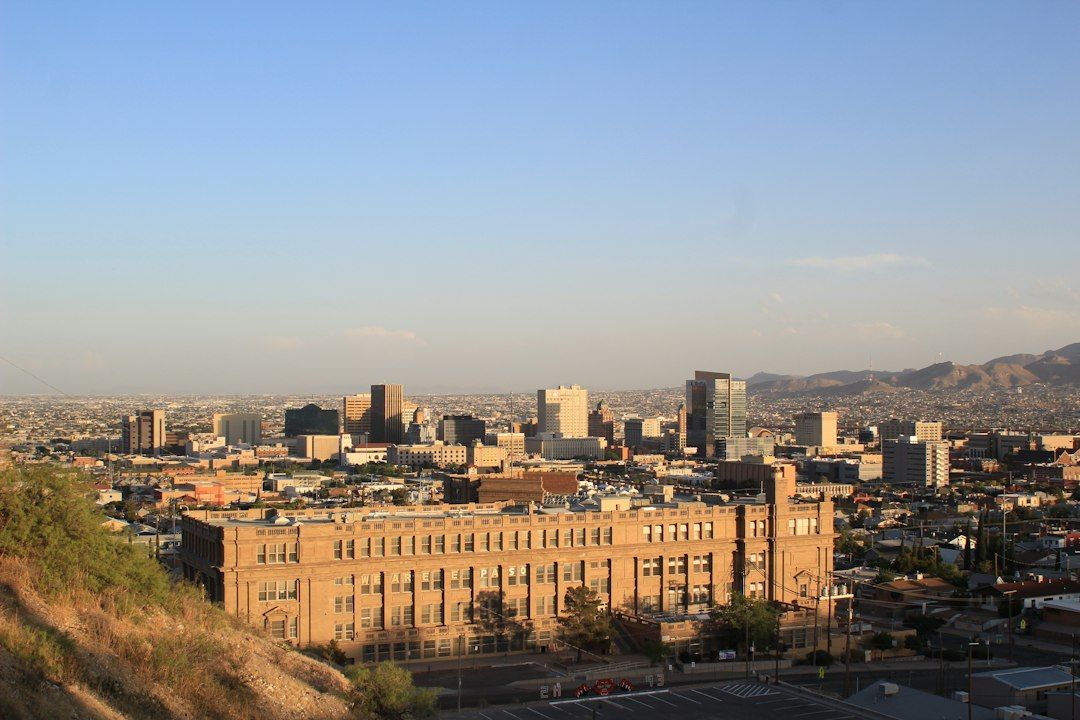
Living on the Border: What El Paso Home and Auto Insurance Should Really Account For
If you live in El Paso, you already know we are not “just another Texas city.” We are a true border community with daily international traffic, desert weather that can turn dangerous quickly, and neighborhood level crime trends that do not always match the rest of the state. Those three realities can shape everything from your deductibles to how (and where) your auto liability applies.
In this article, I will walk through the practical coverage considerations I look at when helping families and drivers choose an El Paso TX insurance company they can rely on, especially when cross-border travel and desert conditions are part of everyday life.
Why El Paso Risk Looks Different Than Most of Texas
Cross-border travel changes the “territory” question fast
A big misconception I see is, “My Texas policy follows me everywhere.” For most U.S. travel, that is largely true. For Mexico, it is not. Mexico generally does not recognize U.S. auto policies as valid proof of liability coverage, which is why travelers are typically advised to purchase a Mexico auto liability policy from a Mexican insurer before driving across. AAA’s Mexico driving insurance guidance explains this clearly and also notes that some U.S. policies may extend limited physical damage coverage near the border, but that does not satisfy Mexico’s liability requirement.
From an underwriting standpoint, regular border crossings can also increase exposure to:
- Higher time-in-traffic and stop-and-go congestion near ports of entry
- More frequent “parking lot” style fender benders
- Higher chance of a claim complication if an accident occurs outside the U.S. If your routine includes Juárez trips for family, work, medical visits, or shopping, your agent should be asking you direct questions about where the vehicle is driven, not just where it is garaged.
Desert weather is not just “heat.” It is wind, dust, and flash flooding.
El Paso weather can be deceptively hard on homes and vehicles. Two patterns matter most for insurance:
- Blowing dust and dust storms: The National Weather Service notes that dust storms can drop visibility quickly and create multi-vehicle pileups. They also recommend specific actions for drivers, like pulling off the roadway and turning lights off once safely stopped. See the NWS dust storm and haboob safety guidance.
- Monsoon season flash flooding: Even in a low rainfall climate, El Paso’s monsoon storms can overwhelm arroyos and streets. El Paso Water’s flood safety page highlights how quickly moving water can become dangerous and reinforces that flash flooding is a real local risk. Review their El Paso flood safety guidance. In plain terms, I have seen more than a few “surprise claims” from clients who assumed flood was impossible because they live in the desert.
Crime patterns influence more than just “peace of mind”
El Paso is often discussed as relatively safe compared with other large cities, but “safer than average” does not mean “no claims.” FBI-based reporting for 2024 shows notable property crime totals, including motor vehicle theft incidents (which directly affects comprehensive coverage, deductibles, and sometimes eligibility depending on carrier appetite). One accessible summary that cites FBI released data is AreaVibes’ El Paso crime stats.
For insurance, the main takeaway is this: your ZIP code and even your side of town can materially affect price, deductibles, and required anti-theft features.
El Paso Auto Insurance: Practical Coverage Choices for a Border City
1) If you cross into Mexico, plan for Mexico liability the right way
From an agent’s perspective, I want your plan to answer two separate questions:
- What happens if my car is damaged in Mexico? (physical damage: comprehensive and collision)
- What happens if I injure someone or damage property in Mexico? (liability) Even when a Texas policy offers some limited Mexico extension for physical damage, it typically does not satisfy Mexico’s legal liability requirement. AAA’s guidance is a good baseline for how travelers should think about it. AAA’s Mexico auto insurance FAQ.
Action steps I recommend before you drive across:
- Ask your agent for your policy’s “territory” wording in writing.
- Confirm whether comp and collision extend at all, and if there is a mileage or time limit.
- Purchase a Mexico admitted liability policy if you are taking your vehicle into Mexico. If you want more detail on smart shopping and what Texas carriers look at, our guide on how independent insurance agencies in Texas help you find the best car insurance plans is a good next read.
2) Dust storms and highway pileups: make sure you are protected when visibility goes to zero
Dust events create a specific kind of auto loss pattern: multiple vehicles, disputed fault, and high total damage. In those scenarios, two coverages become especially valuable:
- Collision coverage (for your vehicle repairs regardless of fault, subject to deductible)
- Uninsured/Underinsured Motorist (UM/UIM) (helps if another driver is at fault but has no coverage or not enough) And if you do a lot of driving, it can be worth exploring behavior-based savings programs. We have a Texas-specific explainer on telematics and usage-based insurance and when it does and does not make sense.
3) Crime and theft: use comprehensive strategically, not emotionally
Comprehensive coverage is what generally applies to theft, vandalism, and many weather losses (not collision). In a city where vehicle theft is a real data point in the FBI reporting summaries, I usually coach clients to think about comp deductibles as a budgeting decision:
- If you can absorb a higher deductible comfortably, raising it can reduce premium.
- If a theft claim would be financially crushing, a lower comprehensive deductible can be a smart trade. Also, if you are shopping price-first, make sure you are not accidentally stripping out protections you rely on. Our article on minimum vs full coverage in Texas helps clarify what you gain and what you give up.
El Paso Home Insurance: Desert Weather, Flash Flooding, and the Claims You Do Not Want to Discover Too Late
1) “Flood” is usually not included in homeowners insurance
This is one of the most important coverage gaps in Texas, including El Paso. Flash flooding can happen fast in monsoon season, and it does not take much water to create major damage to flooring, drywall, and contents. El Paso Water specifically warns that sudden, localized storms can overwhelm arroyos and streets and create dangerous flooding conditions. El Paso Water flood safety information.
If you are near arroyos, low-lying streets, or areas that have taken water before, talk to your agent about flood insurance options early, not when a storm is in the forecast. For a broader Texas perspective, see our Texas flood insurance essentials.
2) Wind, dust, and roof wear: expect maintenance questions from carriers
In West Texas, carriers often pay close attention to roof age and condition because wind driven debris and sun exposure can shorten roof life. My advice is to treat your roof like a financial asset:
- Keep documentation of replacements and repairs.
- Photograph the roof condition periodically.
- Ask your agent how the carrier settles roof losses (replacement cost vs ACV on older roofs, if applicable). For a clearer comparison of how Texas home policies handle deductibles and endorsements, our guide on comparing Texas homeowners insurance policies is helpful.
3) Crime and liability: do not ignore personal property and “loss of use”
Even in a city that rates better than many others on certain crime measures, property crime still exists and drives real claims. FBI data summaries for 2024 in common public reports show thousands of property crimes in El Paso. AreaVibes summary of FBI released data.
Homeowners insurance is not just about the structure. Two parts people underinsure all the time:
- Personal property: replace your stuff, not just your walls.
- Loss of use: pays for temporary living expenses if a covered claim makes the home unlivable. If you have not completed a home inventory lately, it is one of the easiest ways to reduce claim stress later.
My Agent-Level Take: How to Choose the Right Insurance Company in El Paso, TX
When clients ask me to recommend an insurance company El Paso TX families can count on, I do not start with logos or commercials. I start with fit. In a border city, “fit” means your carrier and policy must handle:
- Your real driving territory (including Mexico exposure if applicable)
- Weather patterns that include dust storms and flash flooding risk
- ZIP-code level crime realities for theft and vandalism claims
- Claims service that is responsive, because border-area claims can become paperwork-heavy If you are comparing options, our article on Texas auto insurance agencies vs big direct brands explains why local, independent shopping can matter when your risk profile is not “average Texas.”
BIG - Brock Insurance Group
At BIG, Brock Insurance Group, we have spent years helping Texans match coverage to the realities of where they live and drive. El Paso has its own mix of border traffic, desert weather, and local claim patterns, and that is exactly where an independent agency can add value. Instead of forcing you into one company’s box, we can shop multiple carriers and help you compare coverage details that actually matter, like deductibles, theft protections, and how your policy responds when travel takes you toward or across the border.
Reach out to learn how we can help meet your needs. Let’s work together to achieve your goals!
Need coverage advice? Let’s talk.
Get a fast, no-pressure quote and guidance tailored to your needs.