Compare House Insurance Quotes in Texas for Older vs Newer Homes
Texas real estate offers everything from historic midcentury bungalows to brand new subdivisions. But whether you are purchasing a charming vintage property or a recently built custom home, the age of your house will significantly impact your insurance premiums. At Brock Insurance Group, we have spent over 30 years helping Texans navigate these differences.
The Impact of Home Age on Texas Insurance Rates
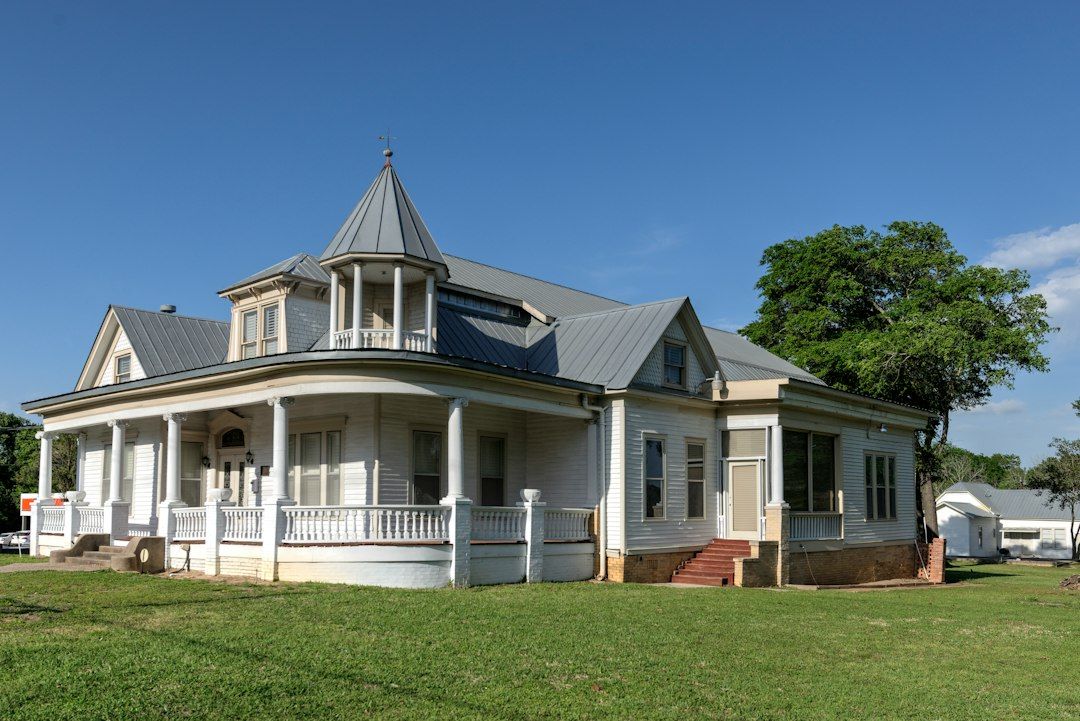
Texas real estate offers everything from historic midcentury bungalows to brand new subdivisions. But whether you are purchasing a charming vintage property or a recently built custom home, the age of your house will significantly impact your insurance premiums. At Brock Insurance Group, we have spent over 30 years helping Texans navigate these differences. We know firsthand that insurers look closely at construction type, age, and recent updates. If you want to compare house insurance quotes, understanding how underwriters view older versus newer properties is the best place to start. Let us break down exactly what affects your rates and how you can secure the best protection for your investment.
Why Age Matters to Underwriters
In recent years, the Texas insurance market has seen significant shifts. With rising construction costs and frequent severe weather events like hail and windstorms, carriers are underwriting homes much more carefully. According to 2025 and 2026 industry data, property premiums in Texas are substantially higher than the national average, making it essential to understand what is driving those costs.
One of the most critical factors is the age of the home, and more specifically, the age of its core components. Insurers love new homes because they feature modern electrical systems, current plumbing standards, and brand new roofs. These elements statistically reduce the likelihood of fire, water damage, and weather related claims. As a result, when you look at house insurance quotes, a newly built home will almost always command a lower base premium than a house built 40 years ago, assuming similar size and location.
For older homes, carriers see increased risk. Outdated wiring or aging galvanized pipes can easily lead to costly claims. But perhaps the biggest focus right now is the roof. Nationwide, roof related claims have skyrocketed, leading Texas insurers to heavily penalize older roofs. If a roof is older than 10 to 15 years, many carriers will only offer Actual Cash Value (ACV) coverage instead of Replacement Cost Value (RCV). This means that if a hailstorm destroys your 15 year old roof, the insurance payout will deduct for 15 years of depreciation, potentially leaving you with thousands of dollars out of pocket.
If you are trying to understand the average cost of home and car insurance in Texas, you must factor in these age related risks. Older homes simply require more maintenance, and without proof of recent updates, insurers will price that risk into your policy.
Key Aspects of Insuring Different Construction Types
When evaluating an older home versus a newer one, the building materials and recent renovations dictate the coverage options available to you.
For example, consider a home built in 1980 that has never had its major systems updated. To get coverage, an insurer might require a four point inspection covering the HVAC, electrical, plumbing, and roof. If you pull house insurance quotes online for this type of property, you might see fewer carriers willing to offer a policy, and those that do will likely include higher deductibles or exclude certain coverages like water backup.
Conversely, a newly built home often qualifies for multiple discounts. New builds typically use modern, wind resistant construction techniques and might even feature impact resistant roofing materials. These upgrades make the property much more attractive to carriers. If you are a new buyer, you can often find excellent deals, such as the cheapest auto and home insurance bundles in Texas for first-time homebuyers, because bundling a brand new, low risk home with your auto policy creates an ideal customer profile for the insurer.
Another aspect to consider is the coverage type. As mentioned, the shift from RCV to ACV on roofs is a massive trend in 2025 and 2026. If you are buying an older home, it is crucial to review comparing home insurance coverages in Texas: replacement cost, ACV, and more. Knowing exactly how a future claim would be paid out can help you decide whether to negotiate a new roof into your real estate purchase or budget for an immediate replacement.
Actionable Insights for Texas Homeowners
Whether your home was built in 1950 or 2025, there are strategic steps you can take to lower your premiums and improve your protection.
If you own or are buying an older home, documentation is your best friend. Keep detailed records of any updates to the electrical panel, plumbing, or HVAC system. Most importantly, if you replace the roof, notify your insurance agent immediately. A new roof can often transition your policy back to highly desirable Replacement Cost coverage and remove strict age related surcharges. When you are ready to shop the market, use a structured approach to compare home insurance quotes so you can see exactly which carrier is rewarding you for those updates.
If you have a newer home, do not get complacent. While your initial rates might be fantastic, you still need to ensure your dwelling coverage keeps pace with Texas's rising construction and labor costs. Review your policy annually to confirm your replacement cost limits are sufficient.
When you generate insurance quotes, home insurance should not be treated as a simple commodity. It is a critical safety net. Instead of relying solely on automated online tools, working with an independent agency allows you to shop across an extensive carrier network. We can help you navigate the nuances, like understanding how to get a Texas homeowners insurance policy quote online or through an agent without getting overwhelmed by the fine print.
Conclusion
The age of your Texas home tells an insurer a story about risk. Newer homes generally enjoy lower premiums and broader coverage due to modern materials and pristine systems. Older homes bring character and history, but they also require proactive updates, especially to the roof, to avoid depreciation penalties and high premiums. By understanding how age, construction type, and updates influence your rates, you can make informed decisions that protect both your property and your wallet. Do not wait until a storm hits to find out how your home's age affects your coverage.
BIG - Brock Insurance Group
At Brock Insurance Group, we believe in building long lasting relationships with our clients. Our mission is to provide personalized insurance solutions that protect what matters most. With over 30 years of experience in the Texas market, we understand the unique risks faced by families living in both historic properties and brand new builds. We have the expertise and the extensive carrier network to tailor a plan perfectly suited to your home's specific age and condition. Reach out to learn how we can help meet your needs. Let us work together to achieve your goals! Go BIG, Save BIG!
Need coverage advice? Let’s talk.
Get a fast, no-pressure quote and guidance tailored to your needs.