Insurance Companies in Amarillo, Texas: Wind and Hail Considerations
If you have ever shopped homeowners insurance in the Texas Panhandle, you already know Amarillo is not priced like “average Texas.” Wind and hail are not occasional nuisances here. They are underwriting facts of life that shape which carriers will write policies and what roof terms look like.
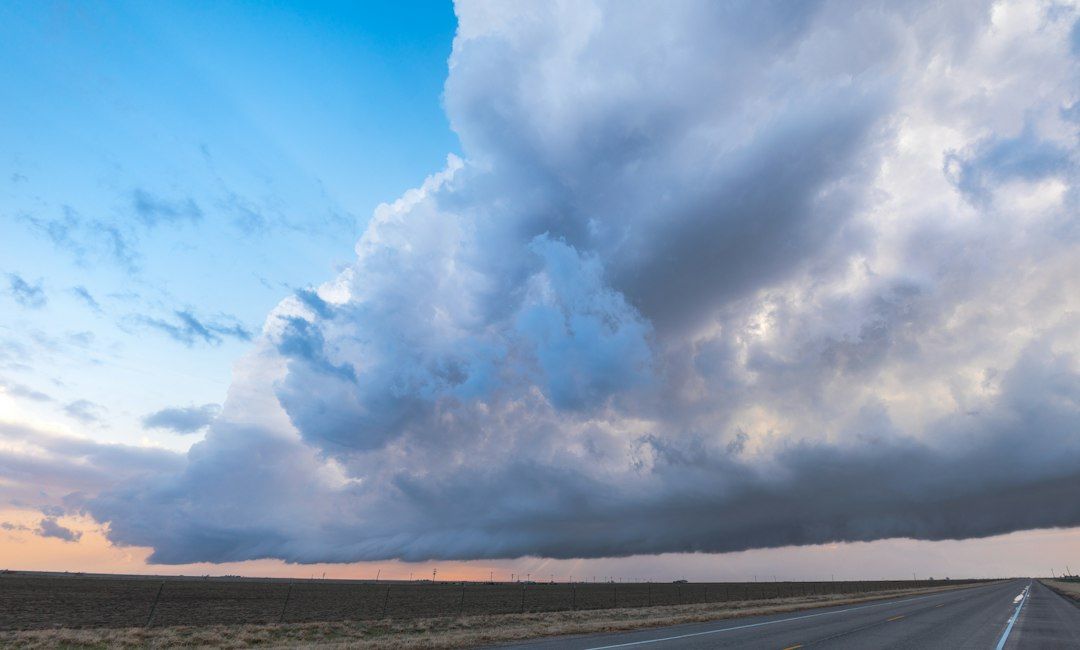
If you have ever shopped homeowners insurance in the Texas Panhandle, you already know Amarillo is not priced like “average Texas.” Wind and hail are not occasional nuisances here. They are underwriting facts of life that shape which carriers will write policies, what roof terms look like, and how much you pay.
A helpful reality check is this: Potter County, where Amarillo sits, has recorded the most days with severe hail in Texas since 2000, based on NOAA Storm Events Database analysis reported by the Houston Chronicle. “Severe hail” in that data means hail at least 1 inch in diameter. (houstonchronicle.com) When we combine that frequency with high straight line winds, it is no surprise that insurer appetite in Amarillo can tighten quickly after an active storm season.
In this article, I will walk you through why insurance companies Amarillo shoppers see different pricing and policy terms, what to watch for when comparing quotes, and how to protect your budget without crossing your fingers every spring.
Why Amarillo’s Weather Changes Insurer Appetite (and Your Premium)
When an insurance company decides whether it wants more customers in a city, it is balancing two things:
- Probability of loss: How often claims happen (hail, wind, wildfire smoke damage, etc.).
- Severity of loss: How expensive those claims are when they happen (full roof replacements, fencing, window screens, shop roofs, HVAC damage).
Hail frequency matters, but roof replacement economics matter more
Hail is a “severe convective storm” peril, which includes hail, tornadoes, and straight line winds. Nationally, this category has become a major driver of insured catastrophe losses. NOAA’s Billion Dollar Disaster reporting shows severe storms are the most frequent type of billion dollar disaster event in the U.S. record since 1980. (climate.gov)
From an underwriting standpoint, the big story is that hail claims are often roof claims, and roof claims are high dollar, high volume, and hard to control without changing policy terms.
Wind is the multiplier that turns damage into claims
Even when hail is the headline, wind is often what turns “cosmetic” into “functional” damage. High winds can:
- Lift shingles and expose underlayment.
- Drive rain under flashing.
- Turn small hail impacts into broken seals, leaks, and interior water damage.
- Increase fence and outbuilding losses that travel with roof claims. For homeowners, that translates into insurers being more cautious about certain roof ages, roof types, and maintenance histories in Amarillo compared to milder Texas markets.
Key Wind and Hail Policy Features Amarillo Homeowners Should Compare
When clients ask me why two quotes differ so much, the answer is usually not only “carrier pricing.” It is almost always the combination of deductible structure and roof settlement language. If you want a quick refresher on how Texas policies differ across home, rental, and commercial coverage, our overview at Property Insurance in Texas: How Home, Rental, and Commercial Policies Differ is a solid starting point.
1) Wind and hail deductibles in Texas are often percentage based
In Amarillo, it is common for wind and hail to have a separate deductible from “all other perils.” And that wind and hail deductible is frequently a percentage of Coverage A (dwelling limit), not a flat dollar amount. The Texas Department of Insurance (TDI) specifically warns consumers that wind and hail deductibles can be higher than other deductibles and encourages homeowners to ask for the dollar amount. (tdi.texas.gov)
What I see in the real world:
- A 1 percent deductible might feel manageable until your dwelling limit rises with replacement cost inflation.
- A 2 percent deductible can quietly become a several thousand dollar check you must write before insurance helps at all. This is one reason Amarillo shoppers sometimes feel like they “have insurance but cannot use it.” The deductible is doing exactly what the carrier designed it to do: reduce claim frequency and limit smaller roof claims.
If you are actively comparing homeowners policies, this pairs well with our deeper guide on Comparing Texas Homeowners Insurance Policies: Limits, Deductibles, and Endorsements.
2) Roof settlement: replacement cost vs actual cash value (ACV)
One of the biggest Panhandle pricing levers is how the roof is paid at claim time.
TDI explains the difference clearly: replacement cost coverage pays the cost to replace (up to your limit) without depreciation, while actual cash value (ACV) subtracts depreciation based on age and condition. In TDI’s example, an older roof can result in little or even zero payment once the deductible is applied. (tdi.texas.gov)
In Amarillo, I often see:
- Carriers offering a lower premium if the roof is settled on ACV after a certain roof age.
- Roof schedules or endorsements that limit payment on certain roof types.
- More scrutiny on documentation of roof updates. Practical takeaway: When comparing “insurance companies Amarillo” quotes, do not compare premium only. Compare premium plus your likely out of pocket cost if a storm damages your roof.
For homeowners who want to go a level deeper into coverage valuation, you might also like Comparing Home Insurance Coverages in Texas: Replacement Cost, ACV, and More.
3) Insurer appetite: why a carrier may pause new business in hail heavy ZIP codes
Amarillo can see sudden market shifts after a bad season:
- A carrier may tighten underwriting and require newer roofs.
- Another carrier may increase minimum deductibles.
- Some may limit coverage on older roofs or certain construction types. This is not personal, and it is not necessarily a sign the carrier is “bad.” It is the carrier managing concentration risk in a hail prone geography.
That is where an independent agency approach matters. Instead of one company, you want access to a broader carrier bench so that when appetite changes, you have options. If you are weighing that decision, our post on Texas Auto Insurance Agencies vs Big Direct Brands explains the difference in a way most shoppers can relate to, even though it is written for auto insurance.
My Amarillo Agent Perspective: How to Shop Smarter for Wind and Hail
After years of reviewing Panhandle accounts, here is the honest guidance I give clients who want strong coverage without paying more than they need.
Treat the deductible as part of your storm plan, not just a number on paper
If your wind and hail deductible is percentage based, ask two questions:
- “What is the deductible in dollars today?”
- “If my dwelling limit increases at renewal, what happens to that deductible?” That conversation alone prevents a lot of surprises. TDI’s consumer guidance is consistent on this point: understand what you will owe before you file a claim. (tdi.texas.gov)
If you are bundling to control cost, you may also find value in Everything Texas Homeowners Need to Know About Home & Auto Bundling, because bundling can sometimes offset part of the hail and wind pricing pressure.
Ask specifically how the roof is settled, especially if it is not new
Do not assume “full replacement” just because the policy is called homeowners insurance. In hail heavy regions, roof settlement terms are one of the first places carriers adjust to keep premiums from becoming unaffordable.
When I review a quote, I look for:
- Roof ACV language and when it applies
- Any cosmetic damage exclusions or limitations
- Separate wind/hail deductible vs all other perils deductible
Reduce loss before it happens because underwriters notice
This is not about being perfect. It is about being insurable at the best tier the carrier offers.
A few improvements that often help, especially during rewrites:
- Document roof age and provide proof of replacement when you have it.
- Keep trees trimmed away from roof edges.
- Consider impact resistant roofing where it makes sense for your budget and neighborhood norms. On the auto side, some of the same “prove you are a better risk” thinking applies. If you are curious how modern insurers reward lower risk behavior, our guide to Telematics & Usage-Based Insurance in Texas is a good read.
BIG - Brock Insurance Group
Amarillo’s weather is not something you can negotiate with, but your insurance strategy is. At BIG - Brock Insurance Group, we help Texas families and small businesses compare carriers based on the details that matter in the Panhandle: wind and hail deductibles, roof settlement terms, and the underwriting rules that can change from one renewal season to the next.
If you are shopping insurance companies Amarillo residents can rely on, or you are simply tired of guessing whether your policy will actually respond after the next hailstorm, let’s talk. Reach out and we will help you sort through the options, explain the tradeoffs in plain language, and build coverage that fits your risk and your budget. Reach out to learn how we can help meet your needs. Let’s work together to achieve your goals!
Need coverage advice? Let’s talk.
Get a fast, no-pressure quote and guidance tailored to your needs.