
Cheap Auto Insurance for High‑Mileage Commuters in Texas
Texans are no strangers to the highway. From the sprawling metroplexes of Dallas and Fort Worth to the long rural stretches connecting smaller towns, getting almost anywhere in the Lone Star State requires a vehicle. For many professionals, a lengthy daily commute is simply a fact of life.
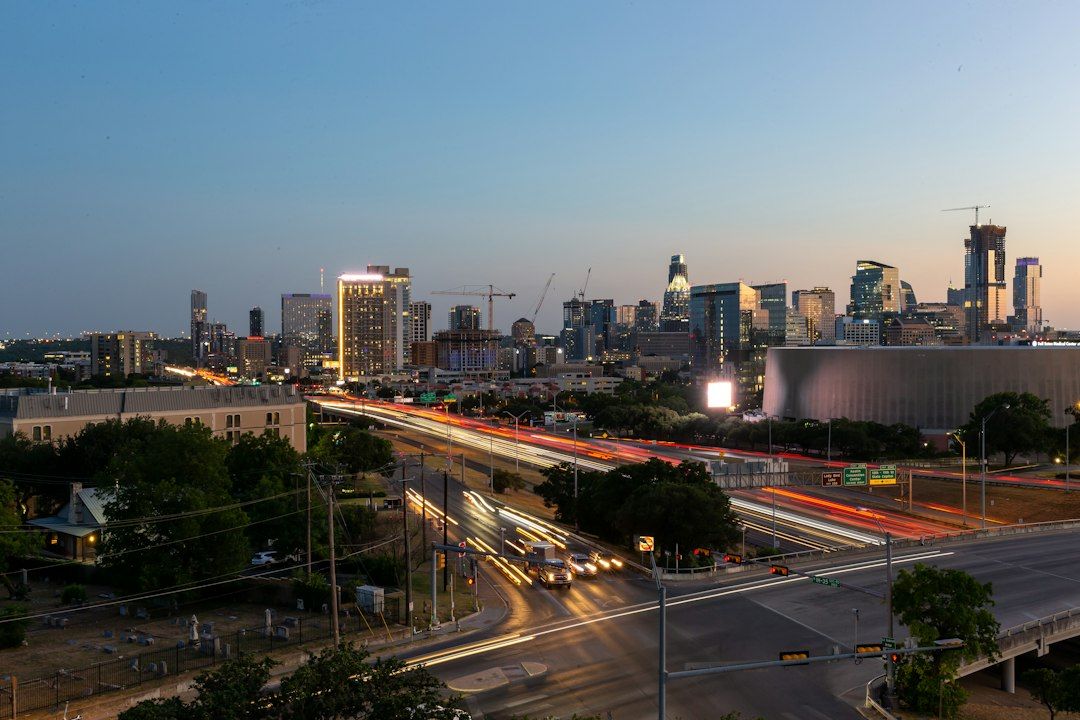
Why Your Texas Commute Drives Up Your Premium
Texans are no strangers to the highway. From the sprawling metroplexes of Dallas and Fort Worth to the long rural stretches connecting our smaller towns, getting almost anywhere in the Lone Star State requires a vehicle. For many professionals, a lengthy daily commute is simply a fact of life. Unfortunately, finding cheap auto insurance in Texas can feel like an uphill battle when you are putting thousands of miles on your odometer every month.
At BIG, we understand the frustration that comes with opening a high renewal bill. With over 30 years of experience serving Texas families and businesses, we have seen firsthand how long commutes impact personal budgets. When an insurance company looks at your profile, your annual mileage is one of the most critical rating factors they consider. The logic from the insurer's perspective is straightforward: the more miles you drive, the more time you spend on the road, which statistically increases your exposure to risks and your likelihood of being involved in an accident.
Recent data highlights just how heavily Texans use their vehicles. According to 2026 industry reports, the average driver in Texas logs over 15,500 miles per year, which is about 2,000 miles higher than the national average. If your commute from the suburbs into a major city center takes 45 minutes or more each way, you are likely surpassing even that high state average. Because of this elevated risk, underwriters automatically apply a higher base rate to high-mileage drivers.
However, a long commute does not automatically condemn you to unmanageable premiums. While you might assume that your rate is set in stone, there are tested ways to secure inexpensive auto insurance in Texas. By understanding how carriers classify your driving habits and knowing which discounts apply to your situation, you can offset the mileage penalty. Our goal is to help you navigate this process so you can keep more money in your pocket without sacrificing the essential coverage you need.
Key Strategies for High-Mileage Drivers
If you are searching for the best low-cost car insurance, you need a strategy that goes beyond simply picking the first online quote you see. High-mileage commuters must be proactive about how their policies are structured. Here are several practical approaches to bring your premiums back down to a manageable level.
1. Calculate Your Exact Mileage
One of the most common mistakes we see drivers make is blindly guessing their annual mileage when setting up a policy. Often, drivers will throw out a conservative guess of 20,000 miles just to be safe. If your actual commute is only 15 miles each way, plus a few weekend errands, you might only be driving 12,000 miles a year.
Insurance carriers rely heavily on the numbers you provide. Overestimating your commute can automatically place you in a higher risk tier. Take ten minutes to map out your exact route to work, multiply it by the number of days you actually drive to the office, and add a reasonable buffer for personal trips. If you work from home two days a week, your annual mileage will be significantly lower than a driver commuting five days a week. Providing an accurate number is the absolute best way to ensure you are not overpaying. If your driving habits have recently changed, reaching out to your agent to learn how to lower your Texas car insurance bill quickly by updating your mileage is a great first step.
2. Embrace Telematics Programs
For drivers who log a lot of miles but practice extremely safe driving habits, telematics can be a game changer. Telematics, or usage-based insurance, involves using a mobile app or a small device plugged into your car to monitor your driving behavior. Rather than pricing your policy entirely on the sheer volume of miles driven, the insurance company looks at how safely you drive those miles.
These programs track metrics such as hard braking, rapid acceleration, phone usage while driving, and the time of day you are on the road. If your long commute is mostly smooth highway driving without aggressive maneuvering, a telematics program can reward you with substantial discounts. Many carriers offer an initial discount just for signing up, followed by a performance-based discount at your next renewal. Exploring telematics and usage-based insurance in Texas is an excellent option for long-distance commuters who want their good driving habits to directly lower their bills.
3. Rethink Your Deductibles and Limits
Finding the best low-cost auto insurance often requires looking closely at how much financial risk you are willing to take on yourself. Your deductible is the amount you pay out of pocket before your insurance coverage kicks in after a covered comprehensive or collision claim.
If you currently carry a $500 deductible, raising it to $1,000 or even $1,500 can noticeably reduce your monthly premium. Because high-mileage drivers face higher base rates for collision coverage, adjusting the deductible provides an immediate offset. You must ensure you have that higher deductible amount set aside in an emergency savings account just in case, but if you go years without an accident, the monthly savings will more than make up for it.
4. Ensure the Correct Vehicle Classification
When an insurance company issues a policy, they categorize the primary use of the vehicle into one of three main buckets: pleasure, commute, or business use.
Pleasure use implies the vehicle is rarely driven for daily tasks. Commute use means you drive back and forth to a single workplace location. Business use means you use your vehicle to visit multiple job sites, transport clients, or make deliveries during the day. Business use carries the highest premium because the driving is less predictable and often occurs during peak traffic hours. If you are a sales representative or contractor who uses a personal vehicle to drive between different job sites across Texas, you must be rated correctly to avoid having a future claim denied. However, if you simply commute to one office building every day, make sure your policy is rated for commuting rather than business use.
Industry Insights: How Carriers View the Commuter Risk
As an independent agency, we monitor the Texas auto insurance market daily. Over the past few years, we have seen major shifts in how carriers underwrite policies. With the rising cost of vehicle repairs, supply chain delays, and increased medical costs following accidents, insurance companies are tightening their guidelines. For high-mileage drivers, this means the penalty for spending more time on the road has become steeper.
However, not all insurance companies view high mileage the same way. This is the secret to finding the most affordable car insurance in Texas. Some standard carriers have a steep price hike once you cross the 15,000-mile threshold. Other carriers have a much flatter pricing curve, meaning the difference in price between driving 10,000 miles and 20,000 miles is relatively small.
This variability is exactly why shopping your rate is so important. If you only look at one or two major brands with massive advertising budgets, you might happen to pick the companies that penalize mileage the most. By working with an independent agency, you gain access to an extensive carrier network. We know which companies cater to long-distance commuters and which ones to avoid. We can help you identify the top car insurance in Texas for high-mileage and commuter drivers by running your specific profile through multiple rating systems at once.
Furthermore, we always advise our clients to keep their credit-based insurance scores in good standing. Texas law permits insurance companies to use your credit history as a factor in determining your premium. A highly favorable credit-based insurance score can drastically reduce your overall rate, often entirely wiping out the premium increase caused by a long commute. Paying your bills on time and keeping your credit utilization low is one of the most effective, albeit indirect, ways to secure affordable car insurance in Texas.
Added Value: A Quick Checklist to Lower Costs Today
If you are a high-mileage driver looking to lower your insurance costs immediately, taking a comprehensive view of your entire household can reveal hidden savings. Here is a quick checklist of actionable items you can review today.
- Bundle Your Policies: We cannot stress this enough. If you own a home or rent an apartment, placing your auto and property insurance with the same carrier is usually the fastest way to drop your rates. The multi-policy discount is significant and can help neutralize a high-mileage penalty. Learning how home and auto insurance bundles really work is essential for any commuter looking to save money.
- Split the Mileage in Multi-Car Households: If you are married or have multiple drivers in your home, consider how your vehicles are assigned. If one spouse works from home and the other commutes 40 miles each way, the commuter should ideally be assigned as the primary driver of the older or cheaper vehicle, if practical. Insuring a brand new luxury SUV for a heavy commute is far more expensive than assigning those miles to an older sedan.
- Check for Affinity Discounts: Many insurance companies offer discounts based on your profession or affiliations. Teachers, first responders, military personnel, and members of certain alumni associations or credit unions often qualify for rate reductions. Always ask your agent to check for these specific discounts.
- Avoid Small Claims: When you are on the road for hours every week, minor dings, scraped bumpers, and cracked windshields are bound to happen. If the cost to repair a minor issue is only slightly above your deductible, it is usually wiser to pay out of pocket. Filing a claim for a small payout will remain on your insurance record for three to five years, causing your rates to increase and costing you much more in the long run.
Conclusion
A long commute across Texas highways undeniably increases your risk profile in the eyes of insurance companies. More miles naturally lead to more exposure. However, an extended drive to work does not mean you have to settle for exorbitant auto insurance rates. By accurately calculating your driving distance, utilizing telematics programs, choosing the right deductibles, and exploring multi-policy bundles, you can take control of your premiums.
The most critical step is ensuring you are matched with an insurance carrier that treats high-mileage drivers fairly. Because every company uses a different mathematical formula to price their policies, finding the right fit requires options. You do not have to navigate this complex marketplace alone. Partnering with a knowledgeable local professional ensures you receive the protection you need for every mile of your journey without breaking your budget.
BIG - Brock Insurance Group
Ready to protect what matters to you without overpaying? Call BIG - Brock Insurance Group today or request a quote online, and let our Texas-based independent team shop multiple top carriers to build a tailored plan for your home, auto, life, business, or farm and ranch coverage. We understand the unique risks faced by families and businesses across the state, and we are committed to finding the perfect balance of comprehensive protection and budget-friendly pricing. Whether you are driving across the county or just down the street, we have the expertise and the extensive carrier network to deliver results. Go BIG, Save BIG!
Need coverage advice? Let’s talk.
Get a fast, no-pressure quote and guidance tailored to your needs.