
Budget-Friendly Car Insurance in Beaumont, Texas
If you live in Beaumont, you know hurricanes and tropical storms are not just headlines on the Weather Channel. From Rita and Ike to Harvey and Imelda, the Golden Triangle has seen repeated flooding, high winds, and long evacuations. Auto insurers watch those patterns closely, and they affect what you pay.
Why Beaumont Car Insurance Costs What It Does
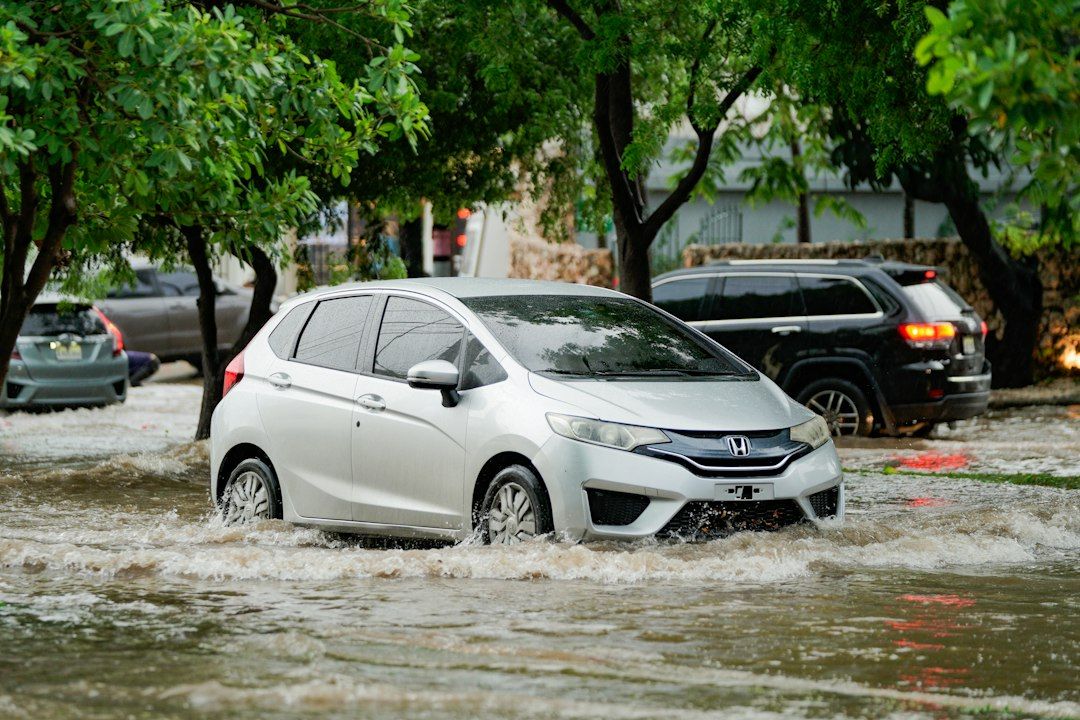
If you live in Beaumont, you know hurricanes and tropical storms are not just headlines on the Weather Channel. From Rita and Ike to Harvey and Imelda, the Golden Triangle has seen repeated flooding, high winds, and long evacuations. Auto insurers watch those patterns closely, and they absolutely affect what you pay for coverage.
The good news: even with coastal exposure and hurricane risk, it is still possible to find budget-friendly car insurance in Beaumont without leaving yourself unprotected. In this guide, I will walk through how insurers look at Beaumont’s risk profile and the practical steps you can take to keep your premium under control while still having the coverage you actually need when the next storm hits.
For a broader statewide view, you can also look at our Texas Car Insurance Quotes Guide.
Beaumont’s Coastal Exposure and Hurricane Risk: What Insurers See
When a company prices auto insurance in Beaumont TX, it looks at far more than your driving record. Rating models pull in location-based data, including:
- Distance to the Gulf Coast and major waterways
- Historical hurricane and tropical storm paths
- Flood, hail, and windstorm frequency
- Local theft and vandalism trends
- Traffic patterns on major routes like I-10 and US 69
Hurricanes and flooding as claim drivers
According to the National Oceanic and Atmospheric Administration (NOAA), the upper Texas coast is one of the most hurricane-prone stretches of shoreline in the country. The Beaumont-Port Arthur area has seen repeated impacts from:
- Major hurricanes like Rita (2005) and Ike (2008)
- Catastrophic rain events and flooding from Harvey (2017)
- Tropical storms like Imelda (2019) that stalled and dumped heavy rain The Insurance Information Institute (Triple-I) notes that severe weather is a primary driver of comprehensive auto claims nationwide. After Hurricane Harvey, Texas insurers handled hundreds of thousands of auto claims, with total insured losses across home, business, and auto running into the billions of dollars.
Insurers use that claims history when projecting future risk. In simple terms:
- More hurricane and flood claims in an area tend to push comprehensive premiums up.
- Areas where cars are frequently totaled or flooded may see higher average payouts per claim.
- Over time, that leads to higher base rates for the ZIP codes most affected.
Beaumont’s geography and industrial footprint
Beaumont is not directly on the open Gulf, but you are close enough that:
- Storm surge, heavy rain, and swollen bayous can flood low-lying roads and neighborhoods.
- High winds can knock over trees, power lines, and debris onto parked vehicles.
- Evacuation traffic on I-10 and surrounding routes increases collision risk when storms threaten. Add in significant industrial traffic around refineries and plants, and you get an environment where both collision and comprehensive losses can run higher than in many inland Texas cities.
That is why someone searching for cheap car insurance Beaumont residents can trust needs to understand that coastal and hurricane risk are baked into the numbers before any discounts or individual factors are even considered.
How Hurricane Risk Shows Up In Your Beaumont Auto Policy
From my side of the desk, I see hurricane-related risk show up in Beaumont auto insurance quotes in a few very specific ways. Understanding these helps you decide where to spend and where to save.
1. Comprehensive coverage and flood-damaged vehicles
Comprehensive coverage is what pays for non-collision damage to your car from things like:
-
Flooding
-
Wind-driven debris
-
Falling trees and limbs
-
Hail
-
Theft and vandalism A few key points for Beaumont drivers:
-
Standard Texas auto policies treat flood as a comprehensive loss, not a separate flood policy like you see with homes.
-
If you only carry liability, hurricane or flood damage to your car is not covered at all.
-
Insurers may price comprehensive higher in Beaumont compared with some inland cities because of repeated storm and flood claims. In coastal and near-coastal Texas, I almost never recommend dropping comprehensive, even on older vehicles. The storm risk is simply too real. Adjusting the deductible is usually a smarter way to control cost than removing the coverage.
2. Evacuations, traffic, and collision claims
Hurricanes do not just damage parked vehicles. They also create:
-
Congested evacuation traffic on I-10 and feeder roads
-
Unfamiliar driving routes for people leaving town
-
Wet roads, limited visibility, and downed signals Those conditions tend to increase collision and accident frequency. Insurers see that in the loss data for coastal and near-coastal ZIP codes. It can translate into:
-
Higher base collision premiums
-
Less aggressive pricing for high-risk drivers in evacuation-prone areas If you are a clean driver with no accidents, this can feel unfair. But from an underwriting perspective, the overall area risk is one part of the price you pay, even before your personal record is factored in.
3. Repair costs after big storms
After a major storm, there is often a surge of:
- Damaged vehicles needing body work and mechanical repairs
- Parts shortages
- Labor shortages or overtime pay at shops That can increase the average cost per claim in a region. Insurers need to anticipate those higher repair costs in their pricing models.
Some carriers also look at how long cars typically spend in the shop during storm surges of claims. Extended repair times can drive up costs for rental reimbursement coverage. Insurers may respond with:
- Higher rental reimbursement rates in high-risk hurricane markets
- Stricter limits on daily or total rental coverage amounts All of this feeds into why insurance Beaumont TX drivers see can feel more expensive than in parts of the state that rarely see named storms.
For a deeper look at how coverage options like rental reimbursement and full coverage affect your bill, you can also review Minimum vs. Full Coverage in Texas.
How To Find Budget-Friendly Car Insurance In Beaumont Without Cutting Corners
The reality is that you cannot change Beaumont’s weather or geography. But you have more control over your premium than most people realize. Here are the levers I encourage my own clients to focus on when they want budget-friendly coverage that still works during hurricane season.
1. Be smart with deductibles, not reckless with coverage
In a hurricane-prone market, the goal is usually: keep the important coverage and fine-tune the deductible.
- Consider higher comprehensive and collision deductibles that you could realistically afford out of pocket if a storm hits.
- Avoid setting the deductible so high that you would not be able to repair your car after a loss.
- Think about where you park and your flood exposure when choosing those deductibles. Raising a deductible is often one of the most effective ways to bring a quote down when you are shopping for cheap car insurance Beaumont drivers can still rely on.
2. Protect your record and consider telematics
Your driving record is still one of the biggest factors in your premium, even with coastal risk baked in. To keep rates competitive:
- Avoid minor at-fault accidents and tickets whenever possible.
- Enroll in a telematics or usage-based program if you are a consistently safe driver. These programs use a smartphone app or device to track habits like braking, time of day, and mileage. Telematics is particularly useful for Beaumont commuters who drive at off-peak times or have shorter daily mileage. Many carriers are now in Texas with these programs, and they can help offset some of the coastal pricing. We discuss this in more detail in our guide to Telematics & Usage-Based Insurance in Texas.
3. Choose liability limits wisely for hurricane country
Texas minimum liability limits are designed to satisfy the law, not necessarily to fully protect your finances. In Beaumont, where there are plenty of newer trucks, SUVs, and commercial vehicles on the road, minimum limits can be used up quickly in a serious crash.
My usual approach with clients:
- Start by understanding what the state requires through resources like Texas Auto Insurance Requirements.
- Price out slightly higher liability limits to see how much extra protection you can get for a modest premium increase.
- Look at your total financial picture (savings, home equity, income) when deciding how much liability protection makes sense. Sometimes we can raise liability significantly for a smaller cost than people expect, which is especially important if a storm-related pileup or serious accident occurs.
4. Use discounts and bundling strategically
In a high-risk weather market like Beaumont, every discount helps. Work with an independent agency that can:
- Compare multi-car and multi-driver discounts across several carriers
- Look at bundling your auto with home, renters, or flood-friendly carriers
- Check for additional discounts for safe driving, defensive driving classes, good student drivers, or certain occupations If you rent, bundling a renters policy with your auto can be surprisingly cost effective. Our broader article on Cheap Car Insurance in Texas: Smart Savings Strategies covers some of the statewide discount options that can apply in Beaumont as well.
5. Work with a local, independent agent who knows storms
One of the most powerful tools you have is guidance from someone who sees what actually happens to claims and premiums before and after major storms.
Independent agents in Southeast Texas can:
- Shop multiple carriers at once, which is critical when some insurers tighten coastal underwriting rules.
- Explain which companies have historically treated storm-related claims fairly and efficiently.
- Help you avoid coverage gaps, such as having liability-only coverage when your car is parked in a flood-prone area. If you have ever wondered whether a local expert can really beat an app-based quote, I recommend reading When a Nearby Insurance Agency Beats Online Quotes for Texas Drivers and Texas Auto Insurance Agencies vs Big Direct Brands. The short version: in coastal and near-coastal areas, local knowledge often pays for itself.
When you are comparing insurance Beaumont TX options, do not be afraid to ask an agent to walk you line by line through how a hurricane or flood loss would play out on competing quotes. The cheapest number on page one is not always the lowest cost after a major storm.
Bringing It All Together For Beaumont Drivers
Living in Beaumont means accepting real hurricane and flood risk, and your auto premium reflects that reality. Insurers look at years of storm paths, flood maps, and claim histories when they set base rates for your ZIP code, then layer on your individual driving record, vehicle type, credit-based insurance score, and coverage choices.
You cannot change the Gulf of Mexico, but you can:
- Keep essential protections like comprehensive in place
- Fine-tune deductibles to fit your budget
- Guard your driving record and consider telematics
- Use smart liability limits, not just the legal minimum
- Take full advantage of discounts, bundling, and a knowledgeable independent agent Handled correctly, budget-friendly does not have to mean bare-bones. It means coverage that is thoughtfully built for Beaumont’s weather, your daily driving, and your financial comfort zone.
BIG - Brock Insurance Group
If you are feeling like your current policy does not match the real storm risk you see every summer and fall, that is exactly the kind of conversation we have with Southeast Texas drivers every day. At BIG - Brock Insurance Group, we understand how Beaumont’s coastal exposure, refinery traffic, and evacuation patterns shape auto insurance, because we have been helping Texas families and businesses navigate these issues for years.
We will walk through your vehicles, parking situation, and budget, then compare carriers that are comfortable with Gulf Coast risk instead of just the cheapest option on a screen. Reach out to our team to talk through your coverage and pricing options. Together, we can build an auto policy that is prepared for the next hurricane season without stretching your wallet more than it has to.
Need coverage advice? Let’s talk.
Get a fast, no-pressure quote and guidance tailored to your needs.